

Payday Advance Borrow Money
by Shpuryk Sergii
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
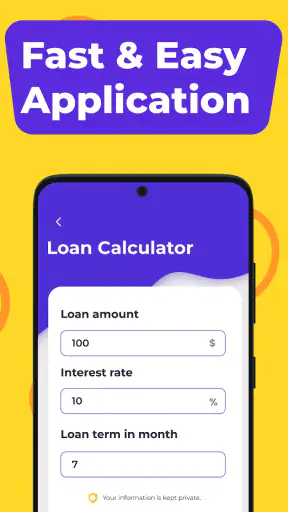
 Analysis by Getfullapps
When an unexpected bill arrives between paydays, the hardest part is often not finding an app but deciding whether borrowing is the sensible answer at all. I approached Payday Advance Borrow Money as a decision tool for that exact moment: a finance app focused on helping users find a suitable payday cash advance. My main takeaway is simple: it can be useful when you need to explore a short-term borrowing route quickly, but it should be treated as a starting point for careful comparison rather than an automatic solution.
The app is free to install, aimed at everyone, and developed by Shpuryk Sergii. It belongs to the payday-advance side of personal finance rather than budgeting, investing, banking, or long-term loan management. That distinction matters. If your goal is to track spending or build savings, this is the wrong kind of tool. If your immediate question is whether a short-term cash advance might fit a temporary gap, its purpose is much more relevant.
How I would decide whether it fits
I would begin with the reason for borrowing, not with the app itself. A small, unavoidable expense with a clear repayment date is a different situation from using borrowed money for groceries every month, covering several old debts, or paying for something that can wait. The app may help you search for an advance, but it cannot make an unaffordable repayment schedule affordable.
The next question is speed versus total cost. Payday products are generally considered because they may address an urgent need more directly than a conventional bank application. That convenience can be valuable, yet urgency also makes it easier to overlook fees, repayment timing, renewal conditions, and the consequences of missing a payment. I would use the app only when I had enough time to read the final offer carefully, even if the original need felt immediate.
A third decision point is how much comparison you want to do. A normal bank, credit union, card provider, or established lending service may offer a different application process and a different cost structure. A cash-advance finder is more appealing when you want to investigate several possible routes from a phone. It is less appealing if you already have a trusted lender with transparent terms and a repayment plan you understand.
One practical habit makes a large difference: before opening the app, I would write down the exact amount needed, the date the money would be available for repayment, and the maximum total I could comfortably return. That prevents the search from becoming a hunt for the largest amount offered. It also gives me a simple way to reject an offer that solves today’s problem by creating a bigger one later.
What the first use is really good for
The strongest role for this app is early-stage discovery. Its store summary presents it as a way to find a suitable payday cash advance, so I would expect the useful moment to be identifying possible borrowing paths rather than managing a complete financial life inside the app. That makes it more focused than a general finance dashboard, but also narrower.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
For example, imagine a phone repair is needed before a work shift and the next paycheck is close. I would enter the situation with a fixed repayment limit, review the available route, and then compare the full repayment amount with alternatives such as asking the repair shop about a delayed payment, using an existing emergency fund, or speaking with my bank. The app earns its place in that process if it helps me investigate quickly without making me feel that accepting the first possibility is the only option.
Another useful workflow is to use it before an emergency, not during the most stressful minute of one. I would install it, understand how the search process is presented, and decide what information I would need before applying. That preparation reduces the chance of entering incomplete details or accepting terms simply because the situation feels urgent. It also lets me compare borrowing with non-loan solutions while I still have time.
The most important insight is that the app should support a borrowing decision, not replace one. A fast path to a possible advance is not the same as approval, guaranteed funds, or a favorable deal. I would regard every result as something to investigate, especially the repayment total and the date on which the obligation ends.
Where this app has an advantage
Its focused purpose is a genuine strength. People who are specifically looking for a payday advance do not need to navigate investment charts, expense categories, or unrelated financial education before reaching the subject that concerns them. The free entry point also makes it easy to explore the app without committing money just to see whether its approach is useful.
The app has also attracted a substantial user base, with more than one hundred thousand installs and an average rating of 4.7 from roughly 3,100 ratings. Those figures suggest that many people find the experience useful enough to rate positively, although they do not tell me whether a particular borrowing offer will suit my circumstances. I would treat the rating as a signal about general reception, not as evidence that every lender or result is equally attractive.
Its suitability for an everyone-rated audience is convenient from an access perspective, but it should not be confused with financial suitability for every person. A broad age classification says that the app can be presented to a general audience; it does not mean that payday borrowing is appropriate for someone with unstable income, existing arrears, or no realistic repayment date.
The current version is 1.2.1, and the minimum operating-system requirement is Android 5.0. That makes the app potentially accessible on older Android phones, which is helpful for users who do not replace devices often. I would still keep the operating system updated where possible and review the information shown during the application process directly, because compatibility alone says nothing about whether a financial product is good value.
Small details that change the decision
First, I would separate the app experience from the lender’s final terms. A smooth search screen can make the process feel simple, but the actual obligation deserves slower attention. Before agreeing, I would check the amount received, the complete amount repaid, the due date, any consequences of late payment, and whether the arrangement involves recurring withdrawals or another automatic collection method. Those are the details that determine whether the advance is manageable.
Second, I would save a private record of the offer before leaving the application flow. A note containing the lender name, borrowed amount, total repayment, and due date can prevent confusion later, particularly if I compare several possibilities. I would not rely on memory or on the assumption that an initial result and a final agreement are identical.
Third, I would use the app to test a smaller, realistic need rather than entering an inflated amount for convenience. Borrowing extra because it is available can turn a temporary shortage into a longer repayment problem. If the smallest workable amount still produces a repayment I cannot cover, that is a clear sign to pause and consider a different route.
Finally, I would avoid treating repeated use as a normal monthly budget category. If I needed a new advance every pay cycle, the underlying issue would probably be a gap between income and essential spending. In that situation, a budget review, creditor discussion, debt-advice service, or lower-cost borrowing option would be more appropriate than repeatedly searching for another payday product.
When a different category is better
A traditional bank or credit union may be a better first stop when you already have an account, a stable income, and time to compare a conventional personal-loan option. The application may feel less immediate, but a longer repayment structure can be easier to manage than a very short deadline. I would especially consider this route when the expense is larger than a single pay cycle can reasonably absorb.
An existing credit card may be more practical for someone who understands its interest rate and can repay the balance promptly. That does not automatically make it cheaper, so I would compare the complete cost rather than choosing it by habit. The advantage is familiarity and an established account; the risk is allowing a one-time emergency balance to become permanent debt.
An overdraft facility can fit a small timing mismatch, particularly when the account provider explains the charges clearly. It can also become expensive if the account remains overdrawn. I would compare the exact repayment timing and charges with any advance found through this app instead of assuming one category is always superior.
For recurring financial pressure, neither a payday finder nor a quick loan search is the right long-term answer. A budgeting app can help reveal where money is going, while a debt-support organization may help prioritize several obligations. Those tools do not provide the immediate cash that an advance is designed to address, but they can deal with the reason the emergency keeps returning.
There is also a non-borrowing category worth considering: negotiating the bill. A utility provider, medical office, landlord, repair business, or service company may have a payment arrangement. Asking does not guarantee success, but it can avoid creating a new credit obligation. I would make that call before accepting a costly short-term advance when the bill is flexible.
What switching away may cost in time and effort
Choosing this app over a bank or another lender is not only about the final amount repaid. It can change how much comparison work I need to do, how many forms I complete, and how closely I must monitor repayment. The convenience of a specialized search can save time at the start, while a conventional provider may require more documentation but offer a relationship I already understand.
Switching from this app to a budgeting tool also means giving up the immediate focus on cash advances. That may feel inconvenient during an urgent situation, but it can be the better trade when the real problem is repeated overspending. I would not switch categories merely because the first search was frustrating; I would switch because the purpose of the tool no longer matches the financial problem.
If I found an offer through the app and then decided to use another provider, I would compare both on the same basis: money received, total repayment, due date, late-payment consequences, and the effect on my next paycheck. Comparing only the advertised amount or the speed of the application creates a false impression of value. The cheapest-looking route is not necessarily the one that leaves the most usable money after repayment.
One friction point is that a finance app can make a serious commitment feel like an ordinary mobile task. I would deliberately slow down at the point where personal details, bank information, or agreement terms are requested. I would also verify that I am dealing with the intended provider and read the privacy and authorization language presented in the app before continuing. Convenience is useful only when it does not weaken basic caution.
Who should use it, and who should skip it
I would recommend trying Payday Advance Borrow Money to an adult who has a specific short-term cash gap, a clear repayment date, and enough income to cover the full obligation without borrowing again. It is also a reasonable fit for someone who wants to explore payday-advance options from a phone before comparing them with a bank, credit union, employer assistance, or a negotiated bill arrangement.
I would advise skipping it if the intended repayment depends on another loan, an uncertain paycheck, or an optimistic estimate of future income. I would also avoid it when the expense is optional, when several debts are already overdue, or when borrowing has become a repeating part of the monthly budget. In those cases, the app may make access easier while leaving the central financial problem untouched.
People looking for expense tracking, savings goals, credit education, investing, or everyday banking should choose a tool built for those jobs. This app’s narrow focus is helpful only when that focus matches the question in front of you. A general-purpose finance app will be more useful for planning; a bank or credit union may be better for a larger, structured loan; and a debt counselor may be better when obligations have already accumulated.
My recommendation after weighing the trade-offs
I see Payday Advance Borrow Money as a convenient research doorway, not a financial safety net. Its free finance-app format, focused purpose, broad device compatibility, and strong overall reception make it worth considering when a short-term advance is genuinely on the table. The developer, Shpuryk Sergii, has kept the product centered on that specific borrowing search rather than turning it into an overcrowded money-management package.
Still, I would never accept an advance simply because the app makes one easy to find. I would compare the complete repayment with at least one alternative, confirm that the due date fits my actual income, and keep a written record of the agreement. If those checks expose a repayment problem, I would stop the process rather than increase the amount or search for another advance.
My final advice is conditional: install it when you need to investigate a temporary cash shortage and are prepared to read every term, but pair it with a realistic repayment plan and a non-borrowing alternative. For a one-off gap that can be closed on schedule, it may save useful time. For recurring shortfalls or larger financial trouble, a different category of help will serve you better.
Pros
- Fast application process with clear borrowing steps
- Useful for covering urgent, unexpected expenses
- Repayment details are shown before accepting an offer
- May help users with limited traditional credit options
- Convenient access from a mobile device at any time
Cons
- Advance fees can make short-term borrowing expensive
- Eligibility and loan terms may vary by location
- Late repayment could lead to additional charges
- Automatic repayment may affect your available bank balance
- Not suitable as a long-term solution for recurring expenses
FAQs for Payday Advance Borrow Money
What is Payday Advance Borrow Money, and how does it work?
Payday Advance Borrow Money is a financial app designed to help eligible users request a short-term cash advance through their mobile device. After creating an account, you generally provide personal, employment, income, and banking details so the service can assess eligibility. If approved, the requested amount may be transferred to your bank account, subject to the provider’s terms, verification process, and available funding options.
How much money can I borrow, and how quickly will I receive it?
The amount available through Payday Advance Borrow Money depends on factors such as your income, banking history, eligibility, state or country regulations, and the lender’s policies. Approval is not guaranteed, and the app may offer different delivery speeds. Some transfers can arrive quickly, while standard bank processing may take longer. Always review the final offer before accepting it.
What fees, interest, or repayment charges should I expect?
Before accepting an advance, carefully check the complete cost of borrowing. Depending on the provider and your location, charges may include an origination fee, service fee, express-transfer fee, finance charge, or other applicable costs. The total repayment amount and due date should be clearly displayed in the offer. Avoid relying only on promotional wording and read every disclosure.
What information and permissions does the app require?
Payday Advance Borrow Money may request information needed to verify your identity, income, employment, and bank account. Depending on the app’s features, it could also ask for permissions related to notifications, device information, or financial-account connections. Only provide data through the official application and review its privacy policy carefully. Do not share passwords, PINs, or security codes unnecessarily.
What happens if I cannot repay the advance on time?
Missing the repayment date can lead to additional fees, failed-payment charges, collection activity, or negative effects on your financial situation, depending on the lender’s agreement and local laws. Contact the provider as soon as possible if repayment may be difficult and ask about available options. Before borrowing, confirm the due date, automatic-debit terms, and consequences of late payment.











